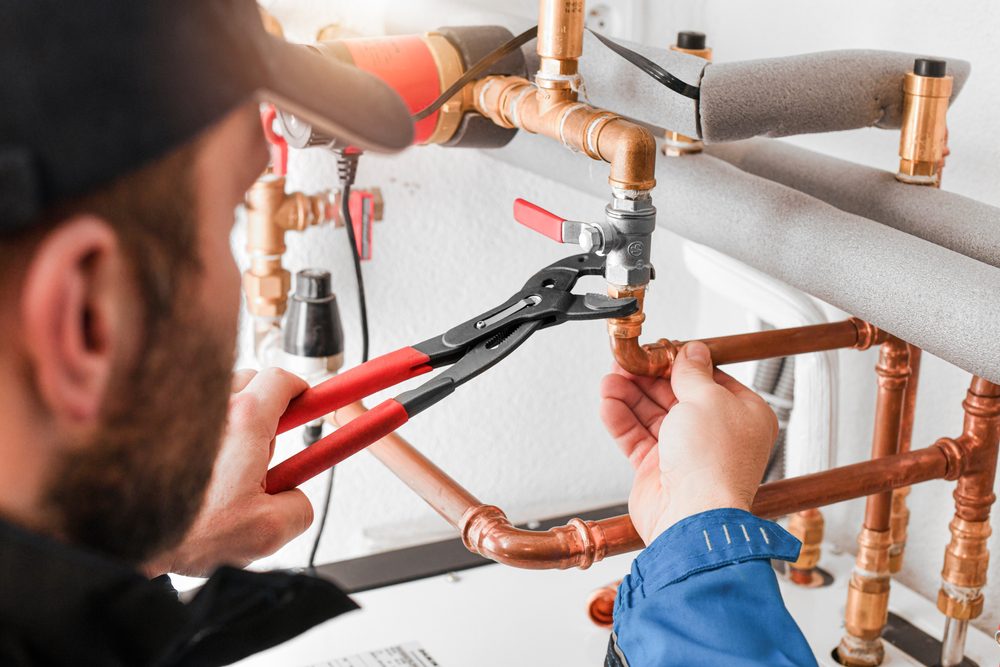
If you run a plumbing business in Kentucky, Kentucky plumber insurance isn’t just paperwork. It’s how you protect cash flow when water, tools, or trucks go sideways. In this guide, I’ll give you a simple checklist, show the most significant cost drivers, and share quick wins to help you lower risk without fluff. I’m Adam Sheridan with Reed Brothers Insurance in Somerset, KY, and we build trade-specific programs for contractors across the state.
Kentucky Plumber Insurance Checklist
Use this before renewals, hiring, or bidding:
-
General Liability (GL) with completed ops — includes additional insured, primary & non-contributory, waiver of subrogation when required by contract.
-
Business Auto / Hired & Non-Owned Auto (HNOA) — schedule all service vans and pickups; confirm personal use rules.
-
Inland Marine (Tools & Equipment) — scheduled high-value items, blanket for hand tools, theft from vehicles covered (with locked-vehicle requirement).
-
Workers’ Compensation (WC) — owners/officers election handled; pay-as-you-go eligible if cash flow is tight.
-
Umbrella / Excess — especially if you work for GCs, schools, or medical facilities.
-
Professional / E&O (design-assist/low-voltage controls/backflow planning) — protects against advice/design mistakes.
-
Cyber (optional) — for invoicing, ACH, and stored customer data.
-
Certificates of Insurance (COIs) — keep templates ready for GCs with additional-insured and waiver language.
-
Subcontractor controls — collect COIs with matching limits, verify active WC, and add hold-harmless/indemnity in your subs’ agreements.
-
Hot work / Soldering controls — written procedure and jobsite checklist (see below).
Pro tip: Build these into your new-hire packet and pre-job checklist so you don’t scramble when a GC requests a COI at bid award.
Top Cost Drivers for Kentucky Plumber Insurance
These rating factors move the price the most:
-
Payroll and class code mix
-
Service/repair vs. new construction vs. commercial/industrial.
-
Gas lines, medical gas, or process piping increase exposure.
-
-
Gross receipts and subcontracted work
-
Percent subbed out and whether you require insured subs with GL + WC.
-
Missing COIs = you’re charged as if you did the work.
-
-
Water damage exposure & controls
-
Open systems, live cut-ins, after-hours callouts, unattended pressure tests.
-
Written water-damage protocol and documentation reduce risk.
-
-
Hot work (soldering/open flame)
-
Torch frequency, fire watch, and jobsite housekeeping.
-
A signed hot-work permit on every job is gold with underwriters.
-
-
Fleet profile
-
Driver MVRs, prior at-fault accidents, garaging, distracted-driving policy, and telematics use.
-
Vehicle security (alarms, locked compartments) affects the likelihood of theft claims.
-
-
Loss history
-
Patterns of small water losses or tool thefts can impact GL, inland marine, and umbrella pricing.
-
Close claims fast; show your corrective actions in writing.
-
Water damage & open flame: quick wins that lower cost
Underwriters scrutinize water losses. Put this Hot-Work & Water-On mini-program in place:
Before work
-
Identify all shutoffs; tag main and fixture valves.
-
Photograph pre-existing conditions; use floor/ceiling moisture readings for baselines.
-
Lay down catch pans and drop cloths; use press-fit caps during breaks.
During work
-
Assign a fire watch with an extinguisher for any torch/solder use (follow 30-minute post-work watch).
-
Never leave pressurization unattended. Use timers on pressure tests.
Water-on testing
-
Pressure test with gauges and documented hold times.
-
Walk all joints dry-to-touch; use paper towels at each union for simple visual verification.
After hours
-
Leave systems valved off when possible.
-
Post a “Water-On Contact” with a 24/7 number on the panel or riser.
Documenting this routine (even a one-page checklist) helps your Kentucky plumber insurance underwriter justify better terms.
Tools & trucks: stop theft before it starts
-
Inventory & marking: Etch or label tools; keep a photographed list tied to serial numbers.
-
Vehicle storage: Locked cabs and bed boxes; park nose-to-building or inside; no tools left in open beds.
-
Alarms & tracking: Van alarms; AirTag/GPS on high-value items and generators.
-
Policy proof: Confirm your inland marine covers theft from a vehicle and any locked-vehicle or forced-entry requirements.
-
Weekend rule: Tools stored indoors when parked >24 hours.
Workers’ Comp Basics for Kentucky Plumber Insurance
-
Class codes split between service/repair and new construction—report payroll accurately to avoid overpaying.
-
Use a return-to-work plan for strains and slips.
-
Consider pay-as-you-go WC so premiums track real payroll and seasonal swings.
-
Collect WC COIs from subs—missing WC pushes their payroll into your audit.
Contracts & COIs that keep you bid-ready
-
Keep standard additional insured, primary & non-contributory, and waiver endorsements ready.
-
Match your limits to typical GC requirements (often combined GL + Umbrella).
-
Build a COI request form on your website so GCs can submit details 24/7.
Getting a quote (simple process)
-
Send your current policy pages, loss runs (3–5 yrs), payroll by class, and vehicle list.
-
Share your water-damage and hot-work checklist.
-
We’ll match markets that actually write plumbers in Kentucky and structure coverage around your jobs.
Next Steps
I’m Adam Sheridan at Reed Brothers Insurance. We work every day with Kentucky plumber insurance programs—from one-truck startups to multi-crew shops.
If you’ve had a renewal jump, started a new crew, or picked up work with tighter insurance terms, let’s review your setup. I’ll help you right-size coverage, clean up paperwork, and press every savings lever that makes sense—without risking the jobs you want.
Call 606-679-6311, email , or request a quote here.
Disclaimer: This article provides general information for Kentucky contractors and isn’t legal or insurance advice. Coverage availability, limits, and eligibility vary by insurer and are subject to underwriting. Your policy’s declarations, forms, and endorsements control. Regulations change; verify Kentucky requirements and consult your licensed agent about your specific operations and contracts.